When people start looking for help with their money, they often come across terms such as financial planner, financial advisor, Investment Adviser and Mutual Fund Distributor. The names sound similar, but the underlying service models can be quite different.
The easiest way to compare them is to look at four things: what the professional actually does, what registration or category applies, how the professional is compensated, and whether products are distributed as part of the service.
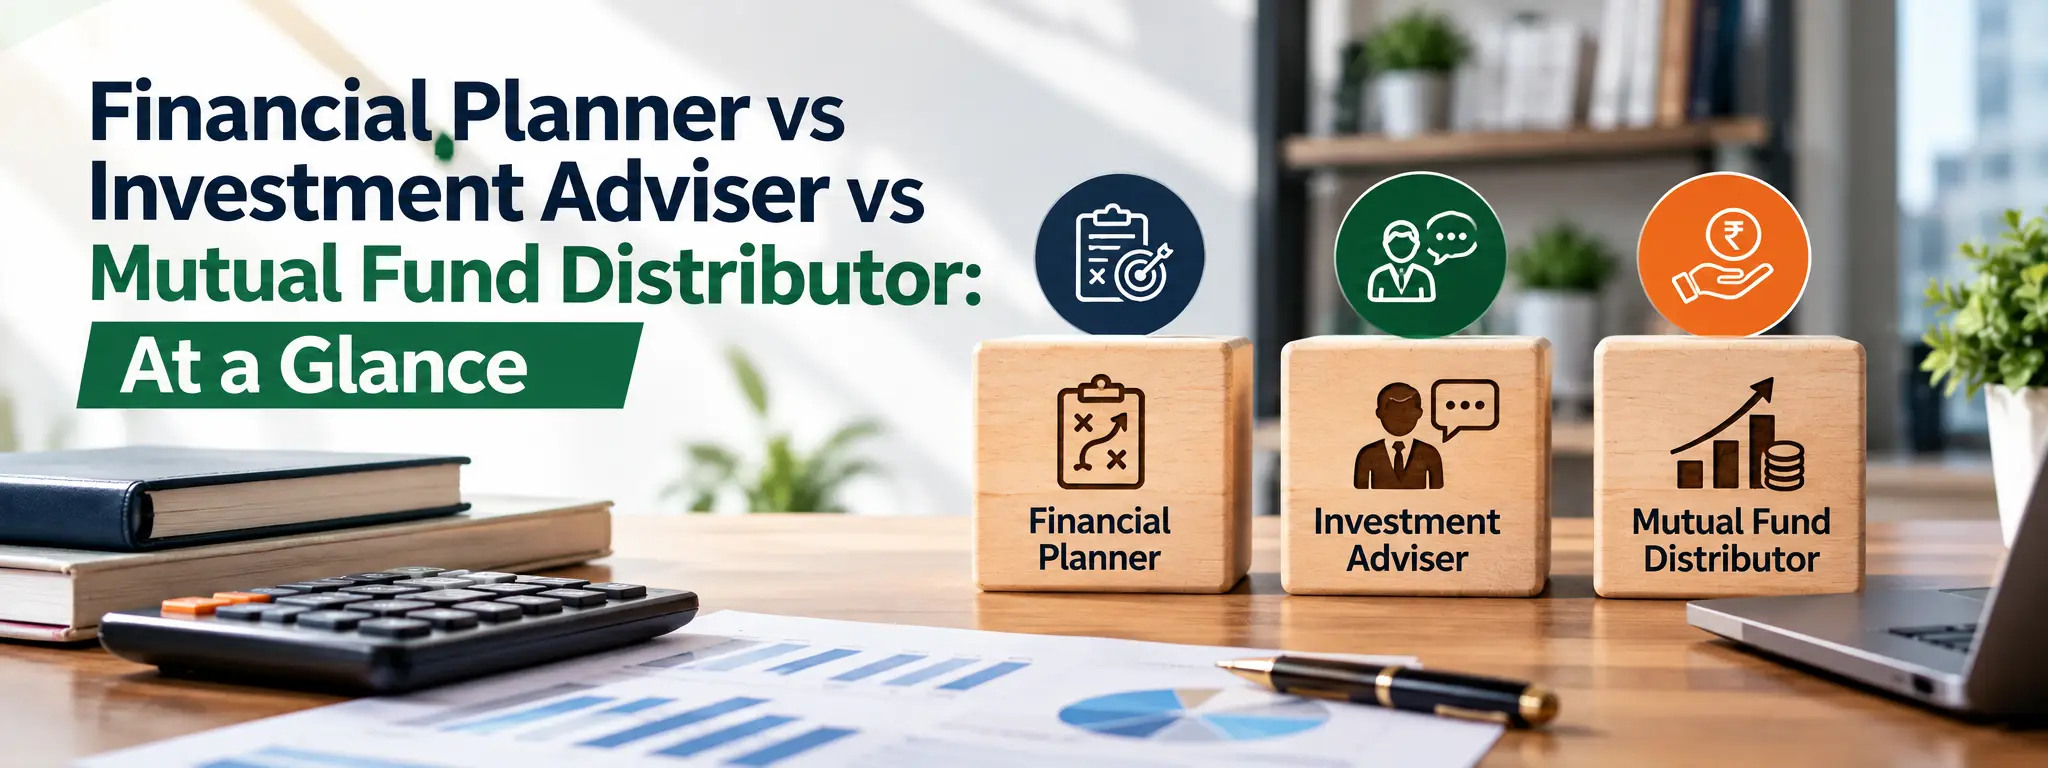
A financial planner is a broad term for someone who helps organise finances around goals. A SEBI-registered Investment Adviser provides investment advice within the SEBI framework. A Mutual Fund Distributor primarily distributes mutual fund products and can provide limited incidental/basic advice within the applicable framework.
Point | Financial Planner | SEBI-Registered Investment Adviser | Mutual Fund Distributor
Primary focus | Overall financial goals and planning | Investment advice | Mutual fund distribution
Regulatory category | Depends on services and structure | SEBI-registered IA | AMFI-registered MFD
Typical scope | Goals, cash flow, investments and planning | Personalised investment advice | Mutual fund products and investor support
Compensation | Depends on service model | Client-fee based advisory model | Trail commission from AMCs on eligible Regular Plan investments
What to verify | Qualifications, experience and actual service scope | SEBI registration | AMFI ARN and applicable EUIN details
Important: the title alone does not tell you a professional’s regulatory status. Before engaging
Important: the title alone does not tell you a professional’s regulatory status. Before engaging anyone, verify the registration category, services offered and compensation model.
What Is a Financial Planner?
Financial planning is about putting different parts of your financial life into one structured plan. Instead of looking at a single investment product, the process can start with your goals, income, expenses, existing assets, liabilities, time horizon and risk tolerance.
Depending on the professional and their scope of work, financial planning may cover:
· Goal setting and prioritisation
· Cash-flow and savings planning
· Investment planning
· Retirement planning
· Portfolio review
· Risk and insurance considerations
· Periodic review as financial goals change
The important point is that “financial planner” is a broad description, not a substitute for checking the actual regulatory category. If you want to understand the broader service, see our financial planning services in India.
What Is a SEBI-Registered Investment Adviser?
A SEBI-Registered Investment Adviser, commonly referred to as an IA, is a professional or entity registered with SEBI to provide investment advisory services under the applicable regulatory framework.
The focus is investment advice tailored to a client’s circumstances. Depending on the engagement, this can involve understanding financial goals, risk profile, investment horizon and existing holdings before providing advice.
If someone claims to be a SEBI-registered Investment Adviser, investors should independently verify the registration through SEBI’s official records rather than relying only on a website or social media profile.
What Is a Mutual Fund Distributor?
A Mutual Fund Distributor (MFD) helps investor’s access mutual fund schemes through the distribution channel. AMFI registration involves an ARN, with applicable EUIN requirements for relevant personnel. AMFI also states that MFDs receive trail commission from AMCs on investments mobilised under Regular Plans.
An MFD’s work can include helping investors understand mutual fund categories, completing transactions, servicing existing investments and providing basic or incidental advice related to mutual fund products within the applicable rules.
SEBI’s current FAQ explains that the incidental activity for an MFD is limited to basic advice relating to mutual fund schemes/products being distributed. A distributor providing investment advice beyond the permitted scope may need registration as an Investment Adviser.
Is a Financial Advisor the Same as a Financial Planner?
Not necessarily. “Financial advisor” is commonly used in everyday language, but the phrase by itself does not tell you whether the person is a financial planner, SEBI-registered Investment Adviser, Mutual Fund Distributor or another type of financial professional.
That is why it is better to ask about the actual registration, service scope and compensation model instead of choosing someone only because their title sounds impressive.
· What is your registration or regulatory category?
· Do you distribute financial products?
· How do you earn from the services you provide?
· Do you charge a separate fee?
· What exactly is included in the service?
Financial Planner vs Investment Adviser
The main difference is the nature of the role. Financial planning can be broader and may bring several financial priorities into one plan. Investment advisory is a specific regulated activity focused on investment advice.
For example, someone looking for help with retirement, cash flow, investment allocation and periodic financial reviews may be looking for a broader planning process. Someone specifically seeking regulated investment advisory services should check whether the professional is registered with SEBI as an Investment Adviser.
Investment Adviser vs Mutual Fund Distributor
This comparison is particularly important because both professionals may discuss investments, but their models are not identical.
Area | Investment Adviser | Mutual Fund Distributor
Regulatory status | Registered with SEBI as an IA | Registered with AMFI as an MFD
Core activity | Investment advisory | Mutual fund distribution
Compensation model | Client-fee based advisory model | Trail commission from AMCs on eligible Regular Plan investments
Product distribution | Subject to applicable SEBI rules | Yes, mutual fund distribution
Verification | SEBI registration | AMFI ARN / applicable EUIN
The right choice is not simply a question of which model is “better”. It depends on whether you need advisory, distribution, broader planning support, or a combination of services that is legally and transparently structured.
Mutual Fund Distributor vs Financial Planner
These roles can overlap in real-world conversations, but they should not automatically be treated as the same.
A financial planning process may start with your complete financial picture and goals. An MFD’s primary role is mutual fund distribution. In practice, an MFD may also provide basic or incidental advice connected to the mutual fund products being distributed, within the applicable framework.
So, if your requirement is broader than mutual fund investing, ask exactly what the professional’s planning service includes and what regulatory category applies to the service.
Direct vs Regular Mutual Fund Plans: Why It Matters
Direct and Regular Plans are two ways investors can invest in the same mutual fund scheme. AMFI explains that both plans have the same common portfolio and fund manager, but their expense ratios differ.
A Direct Plan does not involve a distributor. A Regular Plan is purchased through a Mutual Fund Distributor, and the distributor receives trail commission from the AMC under the applicable commission structure.
Because the expense ratio is different, investors should understand the cost structure before choosing a plan. For a deeper explanation, read our expense ratio guide.
· Direct Plan: no distributor involved and generally lower expense ratio.
· Regular Plan: distributor involved and distribution-related costs are reflected in the scheme’s expense structure.
· Both plans invest in the same underlying scheme portfolio.
· The right choice should consider both cost and the value of the service you need.
How to Verify a Financial Professional before Choosing One
Do not make your decision only on the basis of a website, social media profile, claimed returns or the word “advisor” in a business name. A few simple checks can make the comparison much clearer.
· Check the regulatory category and registration number.
· If the person claims to be a SEBI-registered Investment Adviser, verify the registration on SEBI’s official records.
· For a Mutual Fund Distributor, verify the AMFI ARN and applicable EUIN details.
· Ask how the professional is compensated.
· Ask whether products are distributed as part of the service.
· Ask what is included in the planning, review or advisory service.
· Do not rely on guaranteed-return claims for market-linked investments.
AMFI also provides a distributor locator where investors can search using the distributor name or ARN.
Which One Should You Choose?
There is no single answer for every investor. Start with the service you actually need.
If you need... | Consider checking...
A structured view of multiple financial goals | A financial planning service and the professional’s exact scope
Personalised investment advice under the IA framework | A SEBI-registered Investment Adviser
Mutual fund distribution and ongoing transaction support | An AMFI-registered Mutual Fund Distributor
Help comparing service and compensation models | Registration, fees/commission, products and scope
Where Does Finvriddhi Fit?
Finvriddhi is an AMFI-registered Mutual Fund Distributor with ARN-175717. The Finvriddhi website identifies the business as a registered distributor and offers financial planning and investment-related services.
Our financial planning service follows a structured process that starts with understanding financial goals and the current financial situation, then moves through strategy, implementation and periodic review.
You can also explore our mutual fund investment services if your requirement is specifically related to mutual fund investing.
Finvriddhi’s role should be understood based on its actual registration and services rather than broad labels such as “financial advisor”. Investors should always understand the service model before proceeding.
Questions to Ask Before Choosing a Financial Professional
· What is your registration or regulatory category?
· Are you a SEBI-registered Investment Adviser or a Mutual Fund Distributor?
· Do you distribute mutual fund products?
· How are you compensated?
· Do you charge a separate service fee?
· What services are included?
· How often will my financial plan or portfolio be reviewed?
· Where can I independently verify your registration?
Final Takeaway
The difference between a financial planner, Investment Adviser and Mutual Fund Distributor is not just about job titles. It is about the service being provided, the regulatory category behind it, the way the professional is paid and whether products are distributed.
If you are comparing professionals, do not ask only, “Who is the best financial advisor?” Ask instead: “What exactly do I need, who is authorised to provide it, and how does that professional get paid?”
That simple shift can make it easier to compare financial professionals on facts rather than marketing language.
Frequently Asked Questions
Can a Mutual Fund Distributor give investment advice?
An MFD can provide basic or incidental advice relating to mutual fund schemes/products within the applicable framework. SEBI’s current FAQ states that if a distributor provides investment advice beyond the permitted scope, the relevant SEBI Investment Adviser registration requirements may apply.
Is a financial advisor the same as a financial planner?
Not necessarily. Both terms are commonly used, but the title alone does not establish the professional’s regulatory status. Check the actual registration, services, qualifications and compensation model.
What is the difference between Direct and Regular mutual fund plans?
Both are part of the same mutual fund scheme and have the same underlying portfolio, but their expense ratios differ. Direct Plans do not involve a distributor, while Regular Plans are distributed through an MFD.
Is a SEBI-registered Investment Adviser better than a Mutual Fund Distributor?
Not automatically. They operate under different models. An IA provides investment advisory services under the SEBI framework, while an MFD distributes mutual fund products. The appropriate option depends on your requirement and preferred service model.
How can I verify a SEBI-registered Investment Adviser?
Use SEBI’s official intermediary records to check the adviser’s registration details rather than relying only on the information published by the adviser.
How can I verify a Mutual Fund Distributor?
You can use AMFI’s distributor locator to search by the distributor’s name or ARN and check the relevant registration details.
Does Finvriddhi provide investment advisory services?
Finvriddhi is an AMFI-registered Mutual Fund Distributor with ARN-175717. Investors should review Finvriddhi’s current service and regulatory information before engaging the business.
Commission Disclosure
Finvriddhi is an AMFI-registered Mutual Fund Distributor (ARN-175717). We distribute mutual fund schemes under the Regular Plan and may receive trail commission from the respective Asset Management Companies (AMCs) for eligible investments made through us.
The commission received may vary depending on the mutual fund scheme and AMC. We believe in maintaining transparency about our compensation structure so that investors can make informed decisions.
Disclaimer
Mutual Fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is intended for general educational and informational purposes and should not be treated as personalised investment advice. Regulations, registration requirements and product-related information may change. Investors should verify current registration details, applicable costs and scheme-related information before making financial decisions.